Home / Understanding ATM Skimming: Protect Yourself Against Fraud
Understanding ATM Skimming: Protect Yourself Against Fraud
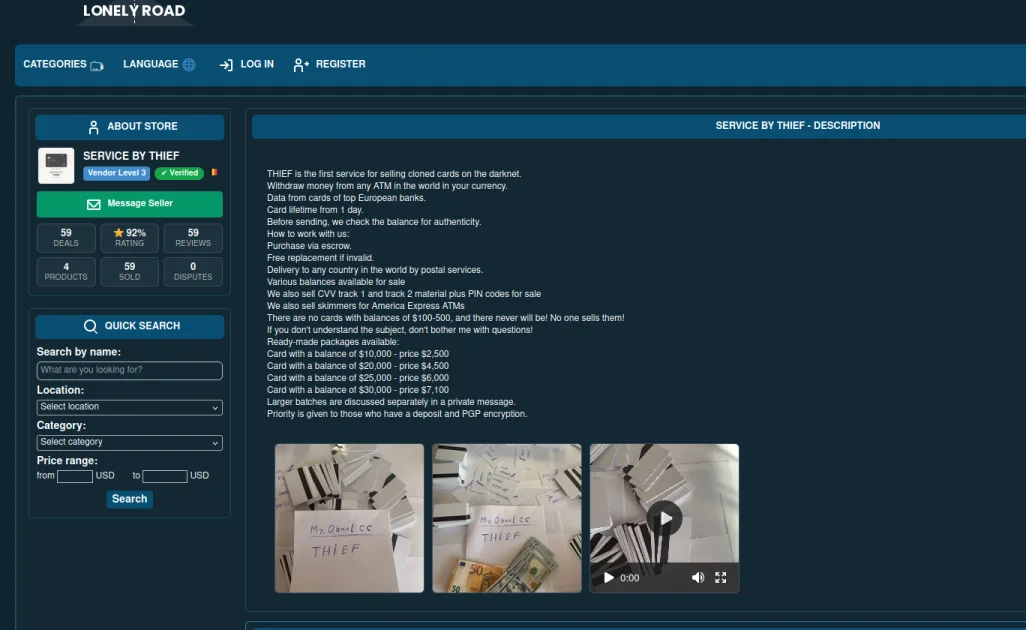
Use Nebula Nexus to examine dark-web claims without treating criminal listings as instructions. If you want to explore Nebula Nexus safely, you should begin with documented outcomes rather than marketplace promises, chat-room boasts, or dramatic video content.
Can You Trust What a Dark-Web Carding Listing Promises?
Can a polished listing prove that cloned cards are profitable and anonymous? No. You may see products, seller ratings, payment details, and confident descriptions, but none of those elements show what happens after a buyer approaches an ATM.
People often assume that carding forums dark web listings describe the full risk — in practice, they describe the transaction from the seller’s perspective. Mark T., a 34-year-old Tampa Bay resident, learned the difference after buying six cloned debit cards with PINs for $480 in cryptocurrency in November 2024.
The cards contained stolen magnetic-track data from real accounts. His first three ATM visits produced $4,200, while a fourth withdrawal added $700 and created the footage that helped identify him.
You can reduce the marketplace story to two conflicting views:
| What you may be encouraged to believe | What the case shows you |
|---|---|
| Cryptocurrency separates a buyer from the purchase | Mark’s purchase of Monero began at a centralized exchange with KYC records |
| A cloned card looks like an ordinary payment card | ATM logs connect the card number, time, amount, location, and transaction result |
| A fast cash-out ends the trail | Investigators followed digital and physical evidence to Mark’s home |
| Darknet access provides real-world anonymity | A 23-second ATM recording captured his uncovered face |
If you encounter discussions labeled cloned cards reddit, card skimming reddit, or cf card cloning, you should not mistake repetition for verification. The supplied case supports a narrower conclusion: buying stolen banking data exposed the buyer to surveillance, a search, arrest, and federal punishment.
How Did the Stolen Data Become Withdrawable Cash?
Was this an elaborate new technique? No. You are looking at a familiar carding chain in which banking data moves from theft to plastic, then from plastic to an ATM.
The sequence in Mark’s case can be organized into five stages:
- Data collection. Criminals obtain magnetic tracks through ATM skimmers, shimmer devices, phishing, data breaches, or purchased dumps.
- Card production. Stolen track data is written onto blank plastic, which may be given a name, number, expiration date, and embossed appearance.
- PIN compromise. An overlay keypad or concealed ATM camera can expose a PIN, allowing a buyer to receive a card prepared for withdrawal.
- Cash-out. The buyer attempts to withdraw funds before the account holder notices and the bank blocks the card.
- Laundering. Cash may be changed into cryptocurrency through a Bitcoin ATM or peer-to-peer exchange.
You should notice where responsibility becomes physical. The marketplace operator can remain distant, but the buyer must carry a card, stand in front of a machine, receive cash, and leave a timed record.
Mark received his cards by mail in neutral packaging after paying in Monero. Everything may have appeared successful to him, yet that appearance ignored the ATM’s role as an evidence-collection system.
Was the Fourth ATM Merely a Cash Machine?
Was Mark interacting only with a device that dispensed bills? No. You should view the ATM in this case as a combination of camera, transaction recorder, location marker, and network endpoint.
The source identifies several records available from modern ATMs:
- A built-in camera directed toward the customer’s face, recording at 1080p and often using infrared illumination at night.
- A second camera, installed in many models at another angle and hidden from outside view.
- A transaction log recording the time to the second, amount, card number, ATM identifier, and transaction status.
- Geolocation information transmitted through the bank’s records.
- Network logs covering processor requests and connection metadata.
At the fourth ATM in a Tampa Bay suburb, Mark wore no mask, glasses, or hat. The camera captured his face in profile while he withdrew $700, took the card, and left; the resulting video lasted 23 seconds.
People often think darknet anonymity continues wherever the purchased data is used — in reality, you cross into a documented physical setting when you use an ATM. The digital purchase and the in-person withdrawal become parts of the same evidentiary chain.
How Quickly Did Investigators Connect the Records?
Did investigators need months to find a buyer hidden behind Tor and Monero? No. You can follow the case from victim complaints to arrest in 15 days, with automated fraud analysis acting before investigators searched Mark’s home.
| Time | What happened |
|---|---|
| Day 1 | Three victims in Florida, Georgia, and North Carolina reported unauthorized withdrawals to their banks. The cards were blocked, and the information entered an early fraud warning system. |
| Day 3 | Bank algorithms recognized rapid withdrawals involving the same group of cloned cards across different states. An emergency alert sent the matter to the bank’s investigators. |
| Day 5 | The bank referred the case to the U.S. Secret Service, which handles financial crimes. An analyst requested ATM logs and recordings. |
| Day 8 | Footage from the fourth ATM supplied a clear face. A comparison with the Florida Department of Public Safety driver’s license database matched Mark, while transaction analysis placed every withdrawal within 40 miles of his home. |
| Day 12 | A warrant covered browser history, ISP information, and crypto activity. Records showed visits to Tor exit nodes around the purchase period, and a court order to the exchange connected Mark’s Monero purchase to his marketplace account. |
| Day 14 | A residential search recovered six blank cards, a magnetic-stripe read/write device, a laptop containing darknet history and Tor traces, shipment packaging, and $3,200 in cash. |
| Day 15 | Mark was arrested and admitted purchasing the cards and cashing out four. The remaining two had been blocked before he tried to use them. |
You should be skeptical of any claim that one privacy tool breaks every connection. Here, timing, geography, bank records, video, exchange identification, computer traces, physical cards, and cash reinforced one another.
Did Monero Make the Purchase Untraceable?
Did a privacy-oriented cryptocurrency erase Mark’s identity? No. You should separate difficulty tracing later Monero movements from the documented point where he acquired it.
Mark used a centralized exchange and completed KYC verification by submitting a passport and selfie. Under a court order, that exchange supplied his identity and transaction history, including a purchase made at the relevant time and in the relevant amount.
Four connections remained available to investigators:
- The entry point. The centralized exchange possessed identity records.
- The time window. The Monero purchase, marketplace order, mailed cards, and ATM withdrawals occurred within two weeks.
- The physical cards. Magnetic tracks on cards recovered during the search matched dumps stolen from actual victims.
- The video. ATM footage placed Mark at the withdrawal site.
People often think anonymous cryptocurrency guarantees an anonymous person — in practice, you must examine where crypto is purchased and where digital value becomes physical cash. Even perfect concealment of later transfers would not remove a face from video or cards from a residence.
Can Skimmer Search Terms Tell You What to Inspect?
Will a page of search results automatically teach you to recognize every skimming device? No. You should check whether the material actually supports its detection claims, and this case source does not provide a visual inspection procedure or validate a consumer device.
Readers may arrive using phrases such as how to tell if a card reader has a skimmer, how to tell if there is a card skimmer, or how to check for credit card skimmers. The documented material establishes that skimmers, shimmer devices, keypad overlays, and hidden cameras can be used to obtain data, but it does not explain how every device looks or how you can reliably identify one.
The same limit applies to product-oriented terms:
| Search phrase you may encounter | What this source lets you conclude |
|---|---|
| credit card skimming device detector | No detector was tested or evaluated in the case. |
| credit card skimmer protection | Faster victim reporting allowed banks to block cards sooner, limiting further withdrawals. |
| credit card skimmer protector | No physical protector was assessed. |
| credit card skimming protection | Bank fraud analysis, transaction records, and customer reports contributed to detection. |
| card skimming protection | The source emphasizes bank systems and timely reporting rather than a named product. |
| card skimming protector | The evidence provides no comparison of commercial protectors. |
| atm skimmer images | No visual identification guide is supplied, so you should not infer one from this case. |
This distinction matters when you explore links, chats, screenshots, or videos. A confident label may attract your attention, but you still need evidence before treating a claim as established.
Which Mistakes Undermined the Buyer’s Anonymity?
Was there one technical failure that exposed Mark? No. You can see several ordinary decisions accumulating until the claim of anonymity became difficult to sustain.
The documented mistakes were straightforward:
- A narrow geographic pattern. All four ATMs were located within 40 miles of his home, giving fraud systems a detectable cluster.
- An uncovered face. Mark used no mask, hat, or glasses, allowing comparison with a driver’s license image.
- A KYC exchange. His passport and selfie connected him to the Monero purchase.
- Evidence stored at home. Investigators recovered cards, an MSR device, packaging, and a laptop with marketplace history and Tor Browser traces.
- Cash retained at home. The seized $3,200 matched denominations dispensed by the ATM and strengthened the case.
- A compressed schedule. The relevant activity occurred within two weeks, making the pattern easier to detect quickly.
The source notes that spreading withdrawals over months might have delayed the automated alert, but it would not have removed the cameras. You should not read that observation as a method; it underscores why timing was only one part of a much broader record.
What Do the Final Numbers Actually Show You?
Did the apparent profit survive the criminal case? No. You should compare the short-lived cash withdrawals with the sentence, restitution, fine, and supervised release.
| Measure | Documented result |
|---|---|
| Cloned cards purchased | 6 |
| Purchase price | $480 |
| Successful withdrawals | 4 |
| Total withdrawn | $4,900 |
| Cash seized at home | $3,200 |
| Time from withdrawal activity to arrest | 15 days |
| Federal prison sentence | 5 years, or 60 months |
| Fine and restitution | $22,000 |
| Supervised release | 3 years |
In March 2025, Mark pleaded guilty to fraud and related activity involving access devices under 18 U.S.C. § 1029, along with money laundering under 18 U.S.C. § 1957. The U.S. District Court for the Middle District of Florida imposed the sentence.
The judge recognized that Mark was a buyer and final participant rather than the organizer. Yet you can see why that position carried the physical exposure: he possessed the cards, visited the ATMs, appeared on camera, and kept evidence at home.
What Should You Take From the Case?
Does this case prove that every carding organizer will be identified? No. You should keep the conclusion narrower because the judge noted that higher-level organizers more often remain hidden and take longer for law enforcement to pursue.
The case does demonstrate how several defensive layers worked together:
- Bank algorithms detected withdrawal patterns before a person conducted the full investigation.
- Victim reports initiated blocking and fraud-warning processes.
- Transaction logs identified the precise footage investigators needed.
- Camera video connected the digital transaction to a person.
- Geography narrowed the search around Mark’s residence.
- Exchange records linked his verified identity to the cryptocurrency purchase.
- The residential search produced cards, equipment, cash, packaging, and computer traces.
People often treat physical security and digital forensics as separate subjects — here, you cannot explain the result without both. The video needed the timed transaction record, while the digital evidence became stronger when investigators recovered matching physical material.
You should apply the same skepticism to dark-web directories and discussion spaces. A listing, chat claim, or video may show you what a seller wants to display, but the criminal proceeding shows the records the buyer failed to see.
Can the Marketplace Story Survive the Evidence?
Was Mark’s downfall caused by one brilliant investigative trick? No. You have seen a chain of routine records, automated alerts, camera footage, KYC data, geographic analysis, and physical evidence turn a $480 purchase into a five-year federal sentence.
When you explore the darker parts of the web, do not confuse access with insight. Check the claims against documented consequences, because the marketplace displayed a product while the ATM, bank, exchange, and search records documented the buyer.